
Kristalina Georgieva says wealthy economies can no longer allow every crisis to leave behind a permanently higher debt burden.
The world’s richest economies have been told to confront a problem that has repeatedly been pushed into the future: soaring public debt and the growing cost of servicing it.
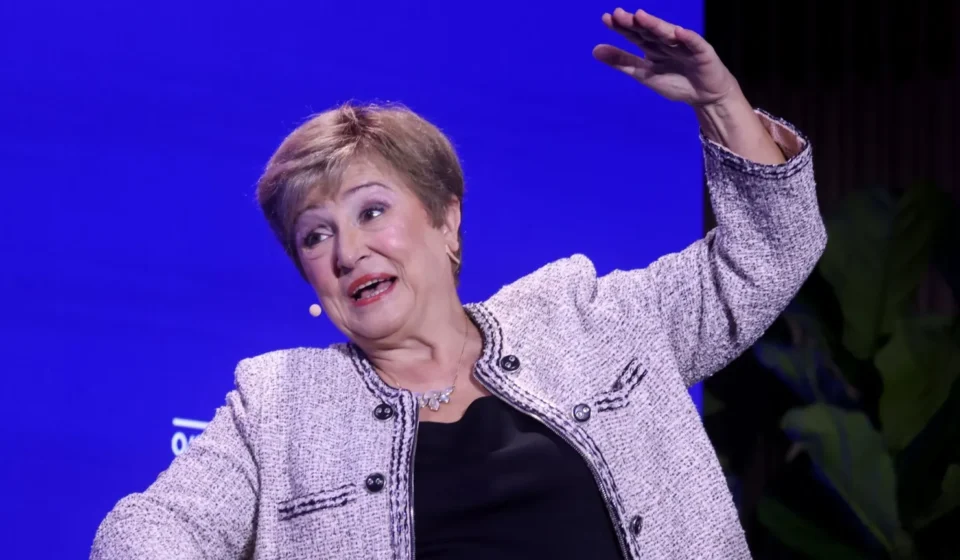
In an exclusive, International Monetary Fund Managing Director, Kristalina Georgieva says governments in advanced economies must begin bringing their debt burdens down rather than allowing each new economic shock to leave public finances permanently more stretched.
Her warning comes as governments face an uncomfortable combination of higher borrowing costs, persistent inflation and geopolitical disruptions that have pushed up energy prices.
Speaking during the United Nations General Assembly in New York, Georgieva compared the trajectory of global debt to a staircase.
Economic shocks, she said, have pushed debt upwards in large steps, while governments have done little to bring it back down once each crisis has passed.
The result is a world in which global public debt is now approaching 100% of GDP, according to the IMF. The Fund has warned that debt is set to rise further.
Her message to advanced economies was direct: governments still have significant control over their domestic fiscal policies, even when they cannot control wars, energy shocks or other external disruptions.
“There are these two things that must be done: bring debt levels down, put fiscal consolidation as a priority, and make sure that the central banks deliver on their mandate for price stability,” Georgieva said.
She acknowledged that such decisions are politically difficult.
“It is impossible to stress strongly enough how critical it is to get the courage to take the steps that are necessary,” she said.
The problem is not simply the size of government debt, it is increasingly about how much governments have to spend servicing it.
When interest rates and bond yields rise, governments must devote more money to interest payments, leaving less available for public services, infrastructure, investment and other priorities.
That pressure is becoming visible in some of the world’s largest economies.
For instance, in Britain, government borrowing reached £18.3bn in August, according to the latest official figures. The figure was £2.9bn higher than a year earlier and £3.5bn above the Office for Budget Responsibility’s forecast.
More striking was the cost of servicing the debt. Interest payments reached £8.8bn in August, the highest August figure since monthly records began in 1997.
Borrowing for the financial year to August stood at £77.3bn, about £8.1bn above the OBR’s forecast. That leaves Britain’s government facing difficult choices as it prepares for its October 28 Budget.
The IMF’s warning therefore arrives at an awkward moment for policymakers already dealing with limited fiscal room.
Across the Atlantic, the United States has reached another striking milestone. US national debt surpassed $40tn in August, according to Treasury data, having more than doubled from its level roughly a decade earlier.
The figure does not by itself mean the US is about to experience a fiscal crisis. The country’s borrowing capacity, economic size and status of the dollar give it financial advantages that many other countries do not possess.
But the growing interest bill is becoming an increasingly important part of the fiscal debate.
The fundamental arithmetic is straightforward: when governments continually run deficits, they borrow to cover the gap. As debt accumulates, interest payments can consume a larger share of future budgets. And if interest rates remain elevated, refinancing existing debt becomes more expensive.
That can create a difficult cycle in which governments borrow more while simultaneously spending more simply to service previous borrowing.
Unfortunately too, wars and disruptions to energy supplies have pushed oil and gas prices higher, feeding into inflation and making it harder for central banks to bring price pressures under control.
The IMF says the global economy has absorbed the recent energy shock better than initially expected, but it continues to regard the shock as an important risk. It has also warned that strategic energy reserves need replenishing while geopolitical uncertainty remains high.